What is a bank statement and what does it show?
A bank statement is an official record of activity in an account over a defined period. For a business, it can help track cash movements, reconcile bookkeeping records and prepare for a funding application. Understanding what is shown on a statement makes it easier to spot missing entries, explain unusual transactions and assess the business’s cash position.
What Is a Bank Statement?
A bank statement is a document issued by a bank that summarises an account’s transactions and balances for a set period, such as a month. It usually identifies the account holder and account, shows money paid in and out, and reports the balance at the beginning and end of the period.
For a business, the statement is a record of what passed through a particular bank account—not a complete picture of every amount the business owes or is owed. For example, an invoice that has been issued but not yet paid will not appear as a deposit until the money reaches the account.
Statements may be provided electronically or on paper. Banks can differ in layout and terminology, but the core information is generally similar. Businesses may need statements when reviewing cash flow, completing a bank reconciliation or preparing documents lenders request for a finance application.
What Information Does a Bank Statement Show?
A statement commonly includes:
- The account holder’s name and account details
- The statement start and end dates
- The opening and closing balances
- Deposits, withdrawals and transfers
- Transaction dates, descriptions and amounts
- Bank charges, interest or other adjustments
A statement period matters because it sets the timeframe for the activity shown. If a business is reviewing a particular month, for instance, the opening balance reflects the account position at the start of that period, while the closing balance reflects it at the end, subject to the bank’s statement conventions.
Descriptions may identify a card payment, transfer or direct debit, but some entries may be abbreviated or unfamiliar. If a transaction is unclear, check the bank’s online transaction details and compare it with invoices, receipts or bookkeeping records.
Business owners exploring how a small business in the UAE can access finance should also understand that a bank statement is only one record of business activity. A finance provider may request other documents to assess the application.
How to Read Balances, Transactions and Fees
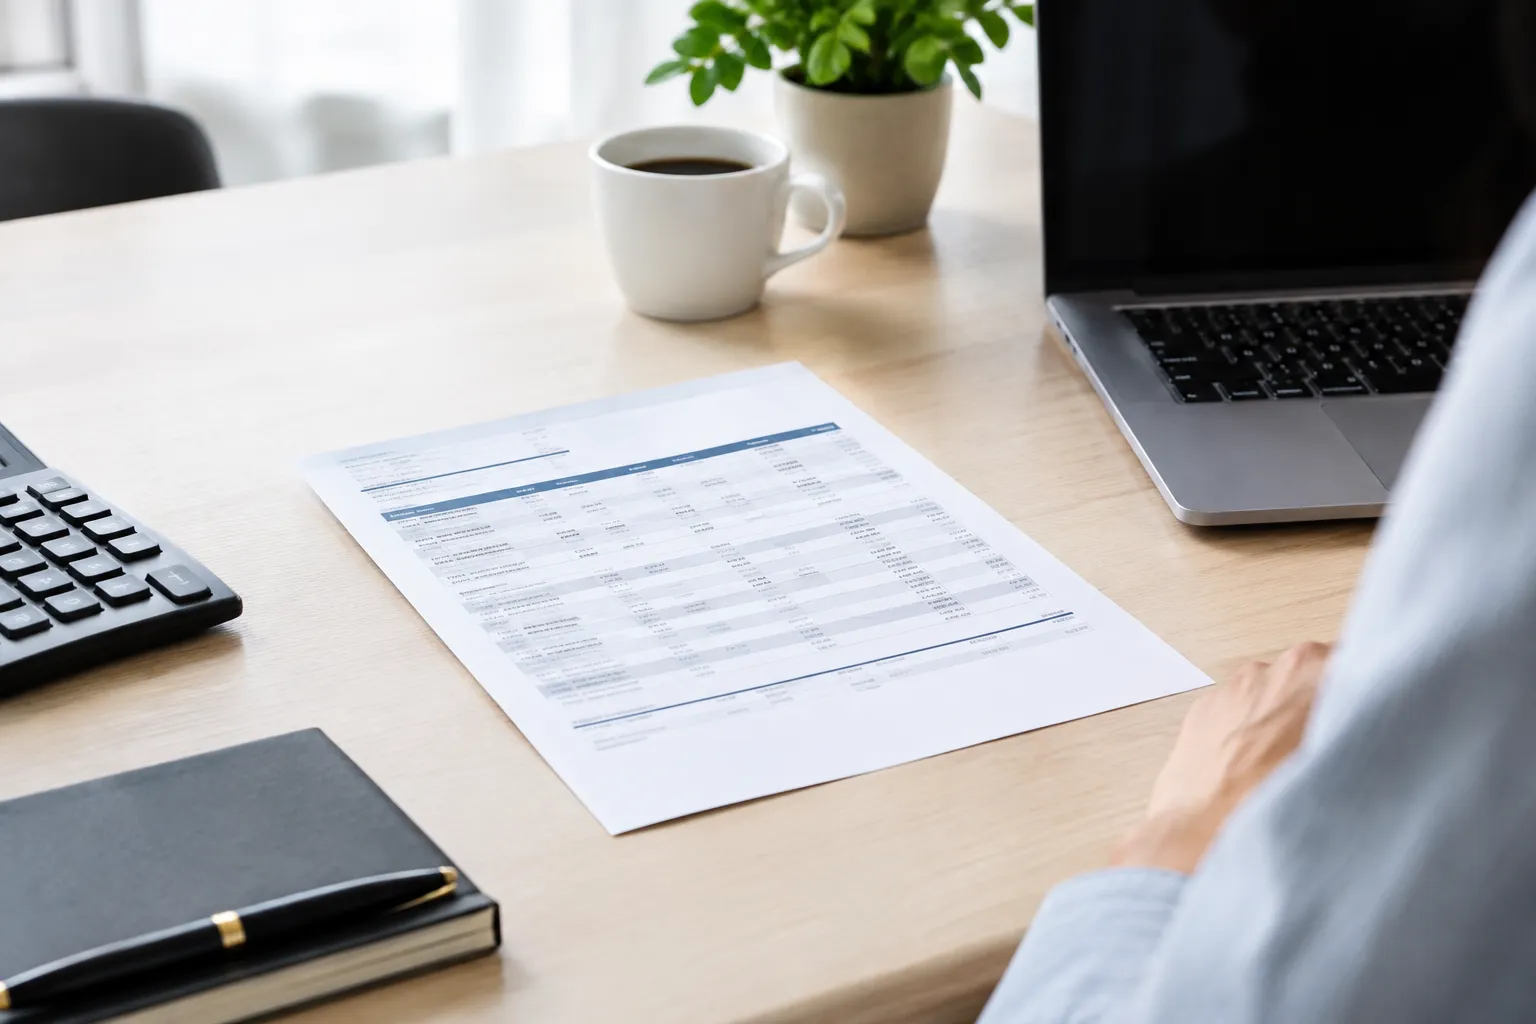
Read a statement in sequence: check the dates and account details, review the opening balance, follow the money in and out, then confirm how the closing balance was reached. A bank statement example can help show how individual entries fit together.
Common transaction types and descriptions
Deposits are amounts added to the account, such as customer payments or funds transferred from another account. Withdrawals are amounts taken out, including supplier payments, card purchases, cash withdrawals and direct debits.
Transfers between accounts may appear as outgoing entries in one account and incoming entries in another. The description might include a payee, payment reference or abbreviated merchant name. Keep supporting records so that entries can be identified later.
A statement does not necessarily explain the business purpose of each payment. For example, a transfer may show the recipient and amount without stating whether it was for stock, rent or another expense.
Opening, closing and available balances
The opening balance is the amount in the account at the beginning of the statement period. The closing balance is the amount recorded at the period’s end after the transactions included in the statement have been applied.
An available balance is the amount the bank currently allows the account holder to use. It can differ from the balance shown on a statement or account screen when transactions are pending, funds are on hold, or payments have not yet cleared. The exact display and timing depend on the bank and transaction.
Fees, interest and other adjustments
Banks may list service charges, transfer fees, interest or corrections as separate entries. These can affect the balance even when they are not customer or supplier transactions.
If a fee or adjustment is unfamiliar, check the bank’s explanation and compare it with the account terms or supporting records. Avoid treating an unexplained entry as an error until it has been checked.
Bank Statement Example and Reconciliation
Bank reconciliation is the process of comparing the transactions and balance on a bank statement with the business’s accounting records for the same period. It helps identify differences that may need investigation, such as a payment recorded in the books but not yet cleared by the bank.
For example, suppose the bookkeeping records show a supplier payment, but it does not appear on the statement for that month. The payment may have been made near the period’s end and processed later. The business should check the payment date and the next statement before deciding that an entry is missing.
Other differences can arise from bank fees not yet entered in the books, duplicate bookkeeping entries or deposits recorded on different dates. Reconciliation means tracing the difference to its source, not changing records simply to make the balances match. Keep a note of any timing differences or corrections made.
Prepare Bank Statements for UAE Business Finance
When a UAE business applies for finance, statements can help a provider understand account activity and cash movement. Requirements vary by provider and facility, so confirm the requested period, account coverage and file format before submitting documents.
Check the statement period and account details
Confirm that the statements cover the full period requested and clearly identify the business and account. Check that every page is included and that the statement dates follow on without unexplained gaps.
If the business uses multiple accounts for operations, note which account receives customer payments and which is used for regular expenses. This context can make the records easier to review, but the provider decides which accounts and documents it needs.
Make transactions easy to understand
Reconcile the statement against bookkeeping records where possible. Check for unrecorded charges, duplicate entries and payments that appear in a different period.
Be prepared to explain unusual or one-off transactions, such as a large deposit, transfer between business accounts or exceptional payment. Supporting records may help clarify the purpose and source of a transaction. For businesses receiving payments against invoices, keep the relevant invoice and payment records together.
Submit clear, unaltered documents
Use complete statements issued by the bank and follow the finance provider’s instructions for format and supporting documents. Do not edit transaction details or remove pages; if something needs explanation, provide a separate note rather than altering the statement.
A clear, consistent set of records can make the business’s financial activity easier to understand. It does not guarantee approval: providers assess applications using their own eligibility requirements and other information.
Bank Statement FAQs
How do I get a bank statement?
Use your bank’s online or mobile banking service to find and download statements, or contact the bank to ask about available options. Check that you select the correct business account and dates.
What do you mean by a bank statement?
A bank statement is a bank-issued record of account activity over a defined period. It shows transactions and balances, including money paid into and out of the account.
What is proof of bank statement?
A bank-issued statement can serve as evidence of activity in a specified account and period. Whether it meets a particular requirement depends on the organisation requesting it.
How to make a bank statement?
You generally do not create an official bank statement yourself; you obtain it from the bank. You can prepare a separate transaction summary for internal use, but it is not a substitute for the bank-issued document.
Can I make my own bank statements?
You can create bookkeeping reports or cash summaries for your business, but you should not present them as bank-issued statements. For verification, provide the document requested by the organisation reviewing your records.
What is an example of a bank statement?
A typical bank statement example shows the account details, statement dates, opening and closing balances, and a dated list of deposits, withdrawals, fees and other transactions.
How many months of bank statements do UAE business lenders usually request?
There is no single period that applies to every UAE finance provider or application. Check the specific provider’s requirements and submit the complete dates requested.
Can a business use statements from more than one bank account in a finance application?
A business may be able to provide statements from multiple accounts if they are relevant, but the provider sets the application requirements. Explain the role of each account and submit only complete, unaltered records.
Use Your Statements to Prepare for Funding
A bank statement helps show how money moved through an account, but it is most useful when read alongside invoices, receipts and accurate bookkeeping records. Reviewing statements regularly can help a business spot unexplained entries, understand cash movement and prepare clearer supporting documents when considering finance.
For a UAE SME, the next step is to match the funding need to the business’s circumstances—whether the pressure relates to working capital, delayed customer payments or a planned purchase. A statement supports that review, but it is not a decision on eligibility or a substitute for advice based on an individual application.
SYG International advises on, structures and arranges debt and equity funding for SMEs and mid-market companies across the UAE, working through banks, fintechs, private lenders and investors. SYG does not lend.
Want to know which funding option fits your business? Talk to SYG International.
Discuss your fundingSYG International advises on, structures and arranges funding. We do not lend. Final decisions, pricing and terms rest with each funding institution. This article is general information, not financial advice.