What is trade finance and how can it support trade?
Trade finance helps businesses manage the gap between paying suppliers and receiving money from buyers. If you are asking “trade finance what is,” the short answer is funding or payment support linked to a trade transaction, such as buying, shipping or selling goods. For UAE importers, it can help make a purchase possible without relying only on available cash or supplier credit.
In brief, trade finance can:
- Support supplier payments while goods are being sourced or shipped.
- Help manage payment risk between buyers and sellers.
- Link funding to transaction documents and the expected proceeds from a sale.
The right option depends on the transaction, documents, timing and ability to repay. Trade finance is not automatically faster or easier to obtain than a bank loan, and approval is decided by the relevant funder.
What trade finance means for UAE businesses
Trade finance is a broad term for financial arrangements that help businesses buy and sell goods. It can address a common timing problem: a supplier may expect payment before goods arrive, while the importer may not receive money from customers until later.
For example, a UAE distributor might need to pay an overseas supplier for stock several weeks before it can sell that stock locally. A trade finance facility may help fund or secure the supplier payment, subject to the transaction and funder’s requirements. The business then repays according to the agreed terms, using cash from sales or another identified source.
This is one form of financing in business: finance connected to a commercial need. It differs from a general-purpose bank loan because the funder may assess the underlying order, supplier, buyer, goods and shipping documents alongside the business itself. A bank loan, by contrast, may be structured around the business’s wider borrowing needs and repayment capacity.
So, whats trade finance in practical terms? It is a way to support a trade transaction when the timing, trust or cash requirements of that transaction make it difficult to proceed using cash alone. It does not remove the risks of importing, selling or collecting payment. The business still needs to understand its obligations and have a realistic repayment plan.
The details vary by funder and facility. A business comparing options should check what the financing is tied to, what documents are needed, when funds or payment commitments become available, and what happens if goods are delayed or a buyer pays late.
For a UAE trading-company perspective on how facilities may relate to day-to-day operations, see trade finance for trading companies.
How trade finance works from purchase order to payment
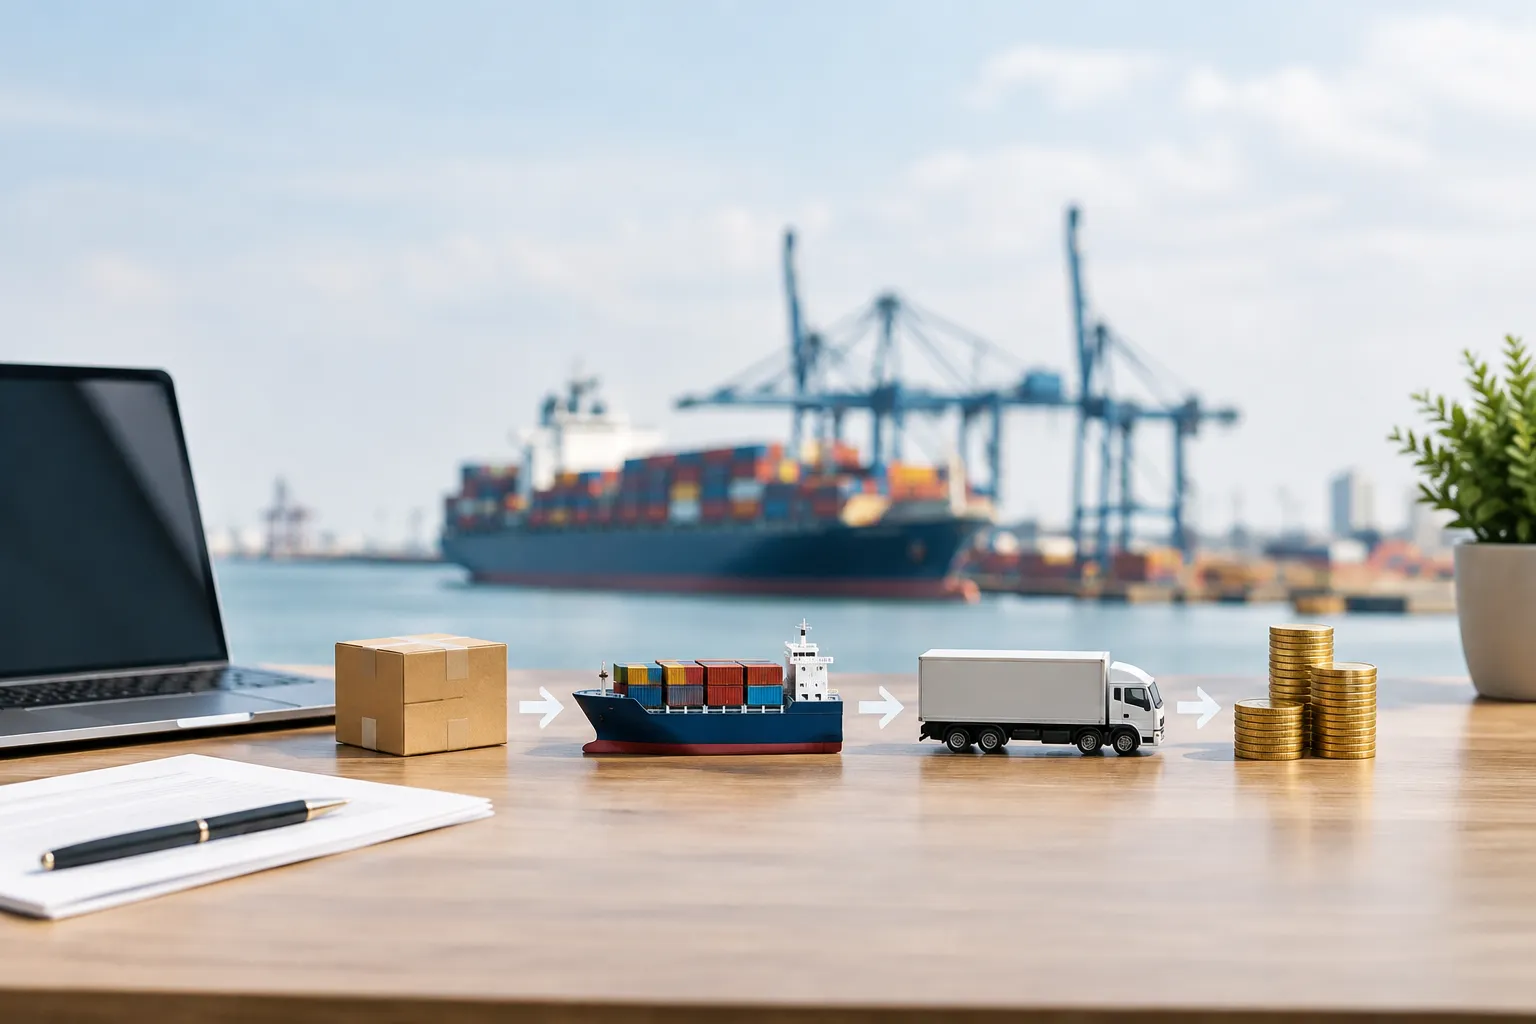
A typical trade transaction involves several parties: the buyer, the supplier, a funder or bank, and transport or logistics providers. The exact sequence depends on the agreement and type of finance. The key is to map when each party must act and when cash is expected to move.
From order confirmation to goods arriving
A transaction may follow this sequence:
- The buyer and supplier agree on the goods, quantity, price, delivery terms and payment terms.
- The buyer issues or confirms a purchase order, and the supplier confirms the order.
- The business assesses its funding need and, if appropriate, applies for a facility before the supplier-payment deadline.
- The supplier prepares and ships the goods according to the agreed terms.
- Shipping and commercial documents are prepared and checked, where relevant to the facility.
- The goods arrive, are cleared and delivered or sold.
- The business pays the funder under the facility terms, using cash from its operations or the proceeds of the sale.
Not every arrangement follows all these steps in this order. Some involve a funder paying the supplier directly; others provide funds to the business or support a payment undertaking. Processing time can depend on the funder’s review, document accuracy, transaction complexity and any required checks. It is prudent to begin discussions before a payment deadline rather than assume funding will arrive by a particular date.
How purchase orders can support funding
A purchase order records a buyer’s intent to purchase specified goods or services. It can help explain the commercial purpose of a funding request, but it is not the same as cash received, and it does not guarantee that finance will be approved.
A funder may consider whether the order is confirmed, whether the supplier can fulfil it, the buyer’s ability to pay, the business’s track record and the expected margin and cash-flow cycle. It may also review contracts, invoices, shipping details and the business’s financial information. Requirements differ, and a purchase order alone may not be sufficient.
When assessing a bank loan or another form of financing in business, explain how the order will turn into repayment. For instance: when the supplier needs payment, when delivery is expected, how long sales may take, and when the business expects to collect from buyers. If the buyer’s payment is delayed, consider how the business will meet repayments in the meantime.
Trade finance tools, including letters of credit
Trade finance includes different tools, not one standard product. Some arrangements help a business access funds for a transaction; others create a payment commitment or manage the exchange of documents. The appropriate option depends on what the buyer and supplier need and what a funder is willing to support.
Letters of credit and documentary collections
A letter of credit is a bank’s undertaking to pay a seller if the seller presents documents that meet the conditions set out in the letter. It can help an importer and exporter agree on a documented payment process, but it does not guarantee that goods will meet the buyer’s expectations. The documents and terms need careful review.
A documentary collection involves banks handling specified shipping and commercial documents according to instructions. Unlike a letter of credit, a documentary collection does not generally create the same kind of bank payment undertaking. The seller’s payment assurance therefore depends more directly on the buyer meeting the agreed payment conditions.
Both methods require attention to detail. Names, dates, amounts, shipment information and document requirements should match the transaction terms. If you are considering this route, read more about a letter of credit for importers.
Supplier payments, trade credit and guarantees
Supplier-payment finance may help a business meet a supplier obligation linked to a trade transaction. Depending on the arrangement, the funder may pay the supplier or provide funds to the business. The business remains responsible for repayment under the agreed terms, even if goods sell more slowly than expected.
Trade credit is different: it is a payment period agreed with a supplier, allowing the buyer to pay later. It can support working capital, but relying heavily on supplier credit may leave a business exposed if terms change or payment is demanded sooner than expected.
A bank guarantee is a commitment issued by a bank in favour of another party, subject to its terms. It may support an obligation, such as a payment or performance requirement, but it is not the same as cash being advanced to the business. If a claim is made under a guarantee, the business may still have obligations to the bank.
These tools should not be treated as interchangeable with a standard bank loan. A loan may provide general funding subject to its own terms; a trade facility may be linked more closely to a particular purchase, sale, payment or document set. Businesses with unpaid customer invoices may also consider invoice financing. See How does invoice financing work for an explanation of how it can relate to delayed receivables.
Documents, timing and common UAE trade scenarios
A funder needs enough information to understand the business, the parties to the transaction and how repayment is expected to happen. Missing or inconsistent paperwork can slow the review or make it harder to assess the request. Prepare documents early, and check that the transaction details agree across them.
Documents funders may ask to review
Requirements vary by provider and facility, but a business may be asked for documents such as:
- Purchase orders, sales contracts or order confirmations.
- Supplier invoices, buyer invoices or pro forma invoices.
- Shipping, transport or delivery documents.
- Details of the goods, shipment route and expected delivery date.
- Company financial information and bank statements.
- Business ownership, registration and identification information.
- Details of existing borrowing and payment obligations.
- Information about the buyer, supplier and expected source of repayment.
The funder may ask for more information after an initial review. For example, it may need clarification about a change in order value, shipment dates, payment terms or the relationship between the parties. Keep electronic records organised and ensure that invoice and transaction data are consistent. E-invoicing readiness can help a business manage and retrieve invoice information, but it does not guarantee funding or replace the documents a provider requests.
When funding may be needed in the trade cycle
Start by identifying the points where money leaves and returns to the business. A simple timeline can show:
- When a deposit or supplier payment is due.
- When goods are expected to ship and arrive.
- When the business expects to sell or deliver the goods.
- When customers are expected to pay.
- When any facility repayment is due.
The gap between these dates is the working-capital need. It may be short or extend across several stages, depending on shipping, customs processes, inventory turnover and customer payment terms. If a buyer pays late, the gap can widen, so test the repayment plan against a delayed-payment scenario rather than relying only on the expected date.
Where there is an urgent supplier demand or a short deadline, contact the relevant funder as early as possible and ask what can realistically be reviewed in the available time. A funding application may take longer than the business has, and approval or disbursement cannot be assumed. Discuss payment terms with the supplier where possible and consider the consequences of taking on a facility that the business cannot repay comfortably.
How UAE importers and exporters use trade finance
A UAE importer may use a trade-related facility to support an overseas stock purchase, where supplier payment falls due before local sales generate cash. A business importing equipment for resale may need to account for the order, shipment, delivery and buyer-payment stages when assessing its funding need.
A UAE exporter may need to pay for inputs, production or logistics before receiving payment from an overseas buyer. The transaction’s buyer, contract terms and supporting documents may be relevant when a funder reviews the request.
Local trade can also create a timing gap. A business buying goods from a UAE supplier may need support if payment is due before it collects money from its own customers. Whether a particular trade finance structure is available depends on the funder and transaction; some options may be more appropriate than a general working-capital facility.
For businesses trading with government-related buyers, payment timing and invoice requirements should be checked carefully. The expected payment source may be relevant to a funding assessment, but it should not be treated as a guaranteed repayment date. Across domestic and international trade, a facility should match the actual transaction rather than a broad assumption about how quickly goods or invoices will convert into cash.
How to assess a trade finance option for your business
A useful comparison starts with the transaction and repayment plan, not just the amount available. Ask what the facility is designed to fund, what conditions apply and whether the expected cash inflow is likely to arrive in time to meet repayments.
Match the facility to the transaction
Write down the key details before approaching a provider:
- What goods or services are being bought or sold?
- Who are the supplier and buyer, and what are the agreed terms?
- How much is due, and on what date?
- When will goods be shipped, received or delivered?
- When does the business expect to receive payment?
- What happens if delivery or collection is delayed?
Then compare the proposed facility with those details. A transaction-linked option may fit a specific supplier payment, while another form of financing in business may suit a broader or recurring working-capital need. A bank loan may be worth comparing if the business needs funding beyond one trade cycle, but it has separate eligibility, repayment and documentation considerations.
Also consider whether the need is temporary or recurring. A one-off purchase with a clear buyer and expected payment date is different from an ongoing cash-flow shortage caused by slow collections or costs that consistently exceed available working capital.
Check costs, conditions and repayment sources
Ask for a clear explanation of all charges and when they apply. Review the repayment schedule, any required security or guarantees, document conditions, and what happens if shipment, delivery or customer payment is delayed. Check whether the facility allows the business enough time to sell the goods and collect payment before repayment falls due.
Identify the repayment source in specific terms. It might be proceeds from a sale, payment of an invoice or other business cash flow. If that source does not arrive on time, the business still needs a plan to meet its obligations. Consider the effect of repayments on payroll, rent, taxes, other suppliers and existing borrowing.
No collateral, no lengthy applications may be an important question for a small business, but neither should be assumed. Ask what security, documents and application steps the provider requires. Compare the total obligations and practical fit, not only the headline amount or speed described during an initial conversation.
Trade Finance FAQs
What is trade finance in simple terms?
Trade finance is funding or payment support linked to buying and selling goods. It can help a business manage the time between paying a supplier, moving goods and collecting money from a buyer.
Is trade finance a good career?
It can suit people interested in banking, international commerce, financial analysis and trade documentation. The role and required experience vary across employers and responsibilities.
Is trade finance risky?
It can involve business, buyer, supplier, shipping, currency and repayment risks. The business should understand its obligations and consider how it would repay if delivery or customer payment is delayed.
Which bank is best in trade finance?
There is no single best choice for every business. Compare providers against your transaction, eligibility, documentation, costs, timing, facility conditions and repayment needs.
Who offers trade finance?
Banks and some finance providers may offer trade-related facilities, with availability depending on the transaction and their criteria. SYG International arranges SME funding solutions across the UAE, including trade finance options.
What skills are needed in trade finance?
Useful skills include reviewing documents carefully, understanding commercial transactions, assessing cash flow and communicating clearly with buyers, suppliers and finance providers.
Can UAE businesses use trade finance for purchases from local suppliers?
Some providers may consider domestic trade transactions, but availability depends on the facility and the parties involved. Ask whether the proposed option covers the specific local purchase and documents.
What should a business do if a trade finance application is delayed?
Ask the provider what information is outstanding and whether a realistic decision date is available. At the same time, discuss payment timing with the supplier and avoid relying on funds until approval and disbursement are confirmed.
Prepare your transaction before approaching a funder
A clear transaction summary can make it easier to discuss suitable funding routes. Set out the supplier and buyer, goods, order value, payment terms, key dates, documents available and the amount of working capital needed. Include the expected repayment source and consider what would change if shipment or customer payment were delayed.
Gather the business and transaction records a provider may request, and check that names, dates, amounts and terms are consistent. If the business has an immediate supplier deadline, explain it early, but do not assume an application can be approved or completed within that period.
Trade finance can support a purchase or sale when payment timing creates a gap, but the facility must fit the transaction and the business’s capacity to repay. SYG International arranges SME funding solutions across the UAE, including debt and equity options through banks and fintechs. Any funding decision remains subject to the relevant provider’s review and terms.
SYG International advises on, structures and arranges debt and equity funding for SMEs and mid-market companies across the UAE, working through banks, fintechs, private lenders and investors. SYG does not lend.
Want to know which funding option fits your business? Talk to SYG International.
Discuss your fundingSYG International advises on, structures and arranges funding. We do not lend. Final decisions, pricing and terms rest with each funding institution. This article is general information, not financial advice.