How to compare loan options for your UAE business
A loan can help a UAE business manage a working-capital gap, purchase equipment or fund planned expansion. The right choice depends on why you are borrowing, how reliably your business generates cash and which repayment commitments it can support.
This guide explains how to compare a business loan, bank loan or small business loan in practical terms. We cover funding purpose, loan structures, eligibility, documents, pricing, collateral and repayment flexibility so you can assess offers more carefully.
Match the loan to your business funding need
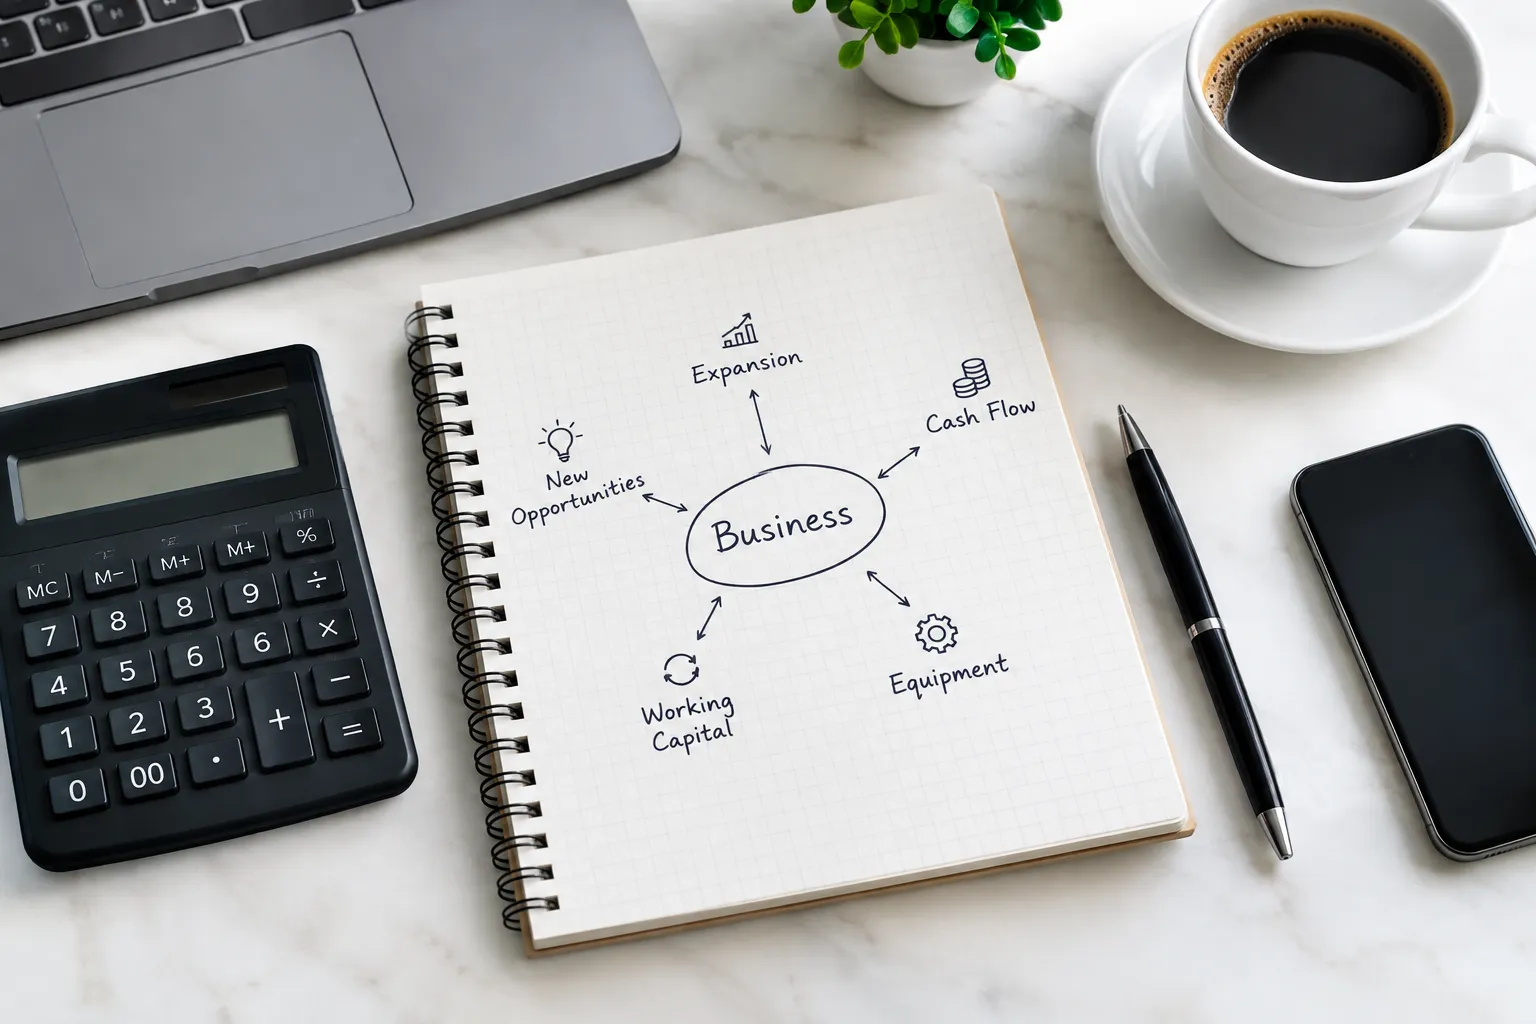
Before comparing lenders or facilities, define the business problem the loan must solve. A clear purpose helps you choose an appropriate amount, repayment period and funding structure.
You can also review the wider UAE SME funding landscape if you are still deciding between debt-based and other funding routes.
Working capital and cash-flow gaps
Working capital is the money a business uses for its normal operating cycle, including supplier payments, payroll, rent and other ongoing expenses. A business may be profitable on paper but still face pressure when customers pay invoices later than expected.
A term loan may be suitable when the funding requirement is identifiable and the business can make regular repayments from expected cash flow. It may help support:
- Seasonal stock purchases
- A temporary gap between supplier payments and customer receipts
- Recurring operating costs during a planned growth period
- A delayed payment from a reliable customer
- A need to reduce dependence on supplier credit
The key tradeoff is that a term loan creates a fixed repayment obligation. If the cash-flow gap is short-lived or unpredictable, a revolving facility may offer more flexibility, subject to its availability and terms. If the gap is caused by unpaid invoices, invoice financing may be more closely matched to the underlying asset than a general-purpose loan.
Before applying, map expected receipts and payments by month. Do not base affordability only on revenue; consider when cash is actually likely to arrive.
Equipment purchases and business expansion
Equipment, vehicles, technology, premises improvements and expansion projects usually require a different assessment from day-to-day working capital. The funding may produce value over several years, so the repayment period should be considered alongside the useful life and expected cash contribution of the investment.
A business loan may fit when:
- The project has a defined cost and implementation plan
- The business can explain how the investment will support operations or growth
- Forecast cash flow can cover repayments without relying on optimistic sales assumptions
- Supplier quotations or project documents are available
- Existing borrowing has been included in the affordability assessment
Asset finance may be worth comparing when the borrowing is specifically tied to an eligible asset. A term loan may provide broader use of funds, but the lender may assess the business purpose, security and repayment capacity differently.
The decision rule is straightforward: borrow only what the project requires, allow for delays or cost changes, and test whether repayments remain manageable if revenue arrives later than expected.
Compare loan options available to UAE businesses
The word loan covers several structures with different uses and risks. Comparing them by interest rate alone can lead to an unsuitable choice. Consider access, repayment, security, flexibility and the reason for borrowing.
Before submitting an application, review the expected paperwork in our guide to loan application documents. Being prepared can make it easier to explain the funding request and respond to lender questions.
Term loans for planned business funding
A term loan normally involves a defined amount, an agreed repayment period and scheduled instalments. This structure can suit a business with a specific investment or a measurable funding requirement.
A term loan may fit when:
- The amount needed can be calculated reasonably
- The business wants a clear repayment schedule
- Cash flow is sufficiently predictable
- The funds will support a defined purpose
- The owners understand the total repayment commitment
Its main benefit is structure: the business knows the borrowing amount and can plan repayments over the agreed term. The tradeoff is reduced flexibility. Borrowing more later may require a new assessment, and repayments generally continue even if the project is delayed.
A term loan is less suitable when the business does not yet know how much it will need or when cash receipts vary significantly from month to month.
Overdrafts and revolving facilities
An overdraft or revolving facility allows a business to draw and repay funds within an approved limit, depending on the provider’s terms. This can be useful for short-term fluctuations, such as timing differences between incoming receipts and supplier payments.
The potential fit is stronger when:
- Funding needs are recurring but uneven
- The business expects regular cash inflows
- The facility will be used for short periods
- The business can monitor its available limit closely
The tradeoff is that access, pricing and renewal conditions can differ from a term loan. A facility that is useful for short-term working capital may become expensive or difficult to manage if the business remains dependent on it continuously.
Compare the approved limit, utilisation rules, review conditions, fees and repayment expectations rather than assuming a revolving facility is automatically more flexible or affordable.
Secured and unsecured borrowing
Secured borrowing involves an asset or other security arrangement that supports the facility. Unsecured borrowing does not rely on the same form of pledged collateral, although a personal guarantee or other obligations may still apply.
Secured finance may be relevant when the business has suitable assets and wants to discuss a structure supported by them. Unsecured borrowing may be considered where the business has sufficient financial strength but limited assets available for security.
Neither structure is suitable for every business. Ask:
- What security is required?
- Who owns the asset?
- What happens if repayments are missed?
- Is a personal guarantee required?
- Are valuation, registration or insurance costs involved?
- Does the security requirement match the amount being borrowed?
A business should understand the legal and financial consequences before offering collateral or signing a guarantee.
Check UAE business loan eligibility and documents
Eligibility is assessed by each bank or fintech provider according to its own criteria. There is no single approval rule for every UAE business, so prepare a clear financial picture rather than relying on a headline eligibility claim.
For background on How can an SME in the UAE approach term-loan funding, consider how the requested amount, business purpose and repayment plan fit together.
What lenders assess
A lender or finance provider may review several parts of the application, including:
- How long the business has been trading
- Revenue patterns and profitability
- Bank account activity
- Existing loans, credit facilities and supplier obligations
- Customer concentration and payment behaviour
- The owners’ background and involvement
- The requested loan purpose
- Forecast cash flow and repayment capacity
- The business’s legal structure and ownership
A strong revenue figure does not by itself demonstrate affordability. Providers may also want to understand whether revenue is recurring, whether receivables are collected on time and whether existing liabilities already place pressure on cash flow.
Explain the funding request in operational terms. For example, describe what will be purchased, when payment is required, how the investment supports the business and which cash flows will be used for repayment.
If the business is facing an urgent supplier demand or delayed customer payment, avoid presenting a short deadline as proof that any facility can be approved in time. Application assessment and disbursement depend on the provider, documentation and circumstances.
Documents to prepare
Typical documents may include:
- Trade licence and company registration documents
- Ownership and identification documents
- Business bank statements
- Management accounts or audited financial statements, where available
- Tax or VAT records, where relevant
- Details of existing borrowing
- Customer invoices, contracts or purchase orders where relevant
- Supplier quotations for equipment or expansion
- A business plan or cash-flow forecast
- Information about proposed collateral or guarantees
The exact list varies by provider and business profile. Keep documents consistent across the application, particularly revenue figures, ownership details, outstanding liabilities and the stated use of funds.
A concise funding summary can also help. It should state the amount requested, purpose, preferred repayment approach, current obligations and the main source of repayment.
Understand loan pricing and the total cost

The cheapest-looking loan is not necessarily the most affordable. Compare the total amount payable, all fees, security obligations and the effect of repayments on monthly cash flow.
Interest rates and pricing methods
Loan pricing may be presented in different ways. A fixed rate may provide more predictable pricing for the agreed period, while a variable rate can change according to the facility terms and relevant conditions.
Also ask whether the calculation uses a reducing balance or another method. Under a reducing-balance approach, interest is generally calculated on the outstanding principal as it declines, but the exact repayment calculation depends on the agreement.
When comparing a business loan or bank loan, ask for:
- The applicable rate and whether it can change
- The calculation method
- The repayment frequency
- The total amount payable
- Any conditions attached to the quoted pricing
- Whether pricing changes after an introductory period
Do not compare one provider’s headline rate directly with another provider’s rate unless the underlying calculation, term, fees and repayment assumptions are comparable.
Fees, collateral and personal guarantees
The total cost may include more than interest. Depending on the facility, ask about arrangement or processing fees, valuation costs, insurance requirements, late-payment charges and early-settlement costs.
Security can also create costs and obligations. If an asset is offered, establish whether valuation, registration or insurance is required. If a personal guarantee is requested, understand how it could affect the guarantor if the business cannot meet its obligations.
Ask for the terms in writing before committing. A lower rate may not represent better value if it comes with higher fees, restrictive conditions or a repayment structure that does not fit the business’s cash cycle.
A qualified financial or legal professional should review the proposed terms for your own circumstances, particularly where personal guarantees, security or debt restructuring are involved.
Choose the right repayment structure
Repayment should be tested against realistic cash flow, not only against the best-case forecast. A loan that appears affordable during a strong month may place pressure on the business during slower periods.
Term length and monthly instalments
A shorter term usually means the balance is repaid sooner, but scheduled instalments may be higher. A longer term may reduce the regular instalment while extending the repayment period and potentially increasing the total cost, depending on the pricing method.
Consider:
- The timing and reliability of customer receipts
- Seasonal changes in revenue
- Existing debt repayments
- Payroll and supplier commitments
- The useful life of the funded asset
- The difference between forecast and actual cash flow
Do not select the longest available term solely to reduce the monthly payment. The term should reflect both affordability and the period over which the funding is expected to create value.
Repayment flexibility and early settlement
Read the repayment conditions carefully. Important questions include:
- On what date are instalments due?
- Is there any grace period?
- Can the business make partial repayments?
- Are extra payments allowed?
- Is early settlement available?
- Are early-settlement charges applied?
- What happens after a missed payment?
- Can the facility be refinanced or restructured?
Flexibility can be valuable when cash flow changes, but it may come with conditions or additional charges. Confirm the practical process for making changes rather than relying on informal explanations.
A practical way to compare offers
Use the same information for every offer and record the results in a simple comparison sheet:
- State the purpose and amount required.
- Record the total payable, not only the quoted rate.
- Calculate the regular instalment and compare it with realistic free cash flow.
- List all fees, insurance requirements and potential charges.
- Note whether collateral or a personal guarantee is required.
- Check payment dates, early settlement terms and missed-payment consequences.
- Review restrictions on how the funds may be used.
- Consider the provider’s questions, process and communication before signing.
The suitable offer is the one whose structure matches the business need and repayment capacity. A lower apparent cost is not useful if the instalments are too difficult to maintain.
Prepare a stronger UAE loan application with SYG International
SYG International arranges SME funding solutions across the UAE, including debt and equity options through banks and fintechs. For businesses specifically considering a term loan, we help clarify the funding requirement and assess potential routes for discussion with finance providers.
A practical preparation process should cover:
- The amount required and how it will be used
- Whether the need is working capital, equipment or expansion
- Current revenue, liabilities and cash-flow pressures
- Documents available for review
- Security or guarantee considerations
- A repayment structure that reflects expected cash flow
- The difference between a general business loan and a more purpose-matched facility
We are not the lender, and approval, pricing, security requirements and timing remain dependent on the relevant bank or fintech provider. The purpose of preparation is to make the business’s position clearer and support a more informed comparison.
Business Loan FAQs
Can I get a 3000 AED salary loan in the UAE?
Eligibility for a personal salary loan depends on the provider’s requirements, income, employer and existing obligations; a business loan is assessed using the company’s financial position and repayment capacity.
Where can a UAE business borrow money urgently?
A UAE business may approach banks, fintech providers or funding arrangers, but urgent timing does not guarantee approval; available options depend on documents, eligibility and the facility required.
How quickly can a business loan be approved in the UAE?
Approval timing varies by provider, application complexity and document completeness. Banks and fintech providers may follow different assessment and verification processes.
Can a new UAE business qualify for a loan?
A new business may face a more limited borrowing assessment because it has less trading history. Providers may instead consider available financial information, owner background, projections and security.
Do UAE business loans require collateral or a personal guarantee?
Not every business loan uses the same security structure. Depending on the provider and application, collateral, a personal guarantee, both or neither may be requested.
Can a business loan be used to repay existing debt?
It may be possible where the provider permits refinancing or debt consolidation, but the business should compare the new total cost, security obligations and repayment period before proceeding.
What happens if a business misses a loan repayment in the UAE?
Consequences depend on the agreement and provider, and may include charges, collection action, credit-record effects or enforcement of agreed security. Contact the provider promptly rather than ignoring the missed payment.
Can a UAE business repay its loan early?
Early repayment may be available, but the agreement can include notice requirements or settlement charges. Ask the provider for the exact settlement amount before making a decision.
Discuss your UAE business funding requirements
Choosing a loan starts with understanding the business need, not selecting the first available offer. Compare the purpose, amount, documents, total cost, security and repayment structure together.
SYG International works with growing UAE SMEs seeking funding for expansion, cash flow or new opportunities. We arrange funding solutions through banks and fintechs, while the final terms and approval remain subject to the relevant provider’s assessment.
SYG International advises on, structures and arranges debt and equity funding for SMEs and mid-market companies across the UAE, working through banks, fintechs, private lenders and investors. SYG does not lend.
Want to know which funding option fits your business? Talk to SYG International.
Discuss your fundingSYG International advises on, structures and arranges funding. We do not lend. Final decisions, pricing and terms rest with each funding institution. This article is general information, not financial advice.