A practical cash flow statement guide for UAE SMEs
A cash flow statement helps a UAE SME understand where cash came from, where it went and whether the business can meet upcoming commitments. Unlike a profit and loss account, it focuses on actual cash movements during a period. This guide explains what is cash flow statement reporting, how to read the three sections, and how the results can inform funding decisions.
What a cash flow statement tells a UAE SME owner
A cash flow statement records cash entering and leaving a business over a defined period, such as a month, quarter or financial year. It normally begins with the opening cash balance, shows movements during the period and arrives at the closing cash balance.
In practical terms, it answers questions such as:
- Are customers paying quickly enough?
- Is the business generating cash from its normal activities?
- How much cash is being invested in equipment, vehicles or expansion?
- Has the business relied on borrowing or owner funding?
- Will available cash cover payroll, suppliers, rent, tax and loan repayments?
The statement is useful for both day-to-day cash flow management and longer-term planning. It can also support a finance application. Businesses preparing for discussions with banks, fintechs or other funding providers may need to organise their SME loan documents, including financial statements and supporting records.
Cash flow versus profit and revenue
Revenue is the value of goods or services sold. Profit is generally revenue less the costs recognised in the relevant accounting period. Cash flow concerns when money actually enters or leaves the business bank account or cash holdings.
For example, a UAE distributor may issue an AED 100,000 invoice in March with payment due in 60 days. The sale may be recorded as revenue in March, but the cash may not arrive until May. If the distributor must pay its supplier in March or April, it can show a profit while experiencing a cash shortage.
The reverse can also happen. A business may receive a loan or an owner contribution, increasing its bank balance without creating revenue. Selling an old vehicle may also bring in cash without being part of normal trading income.
This is why a cash flow statement complements, rather than replaces, the profit and loss account and balance sheet. The profit and loss account helps assess profitability; the balance sheet shows financial position; the cash flow statement explains the movement in cash.
The three sections at a glance
A standard cash flow statement groups cash movements into three categories:
- Operating activities: cash generated or used by normal trading.
- Investing activities: cash spent on or received from long-term assets and investments.
- Financing activities: cash received from or paid to lenders, owners and investors.
The overall calculation is:
Opening cash
+ Operating cash flow
+ Investing cash flow
+ Financing cash flow
= Closing cash
A positive total movement does not automatically mean the business is financially strong. For example, cash may increase because of a new loan while operating activities continue to consume cash. The source of the cash matters as much as the closing balance.
Cash balances and currencies in UAE businesses
Cash usually includes money held in business bank accounts and, where relevant, petty cash. Owners should distinguish business funds from personal accounts and ensure that all accounts used for business activity are included in the reporting process.
UAE SMEs may also invoice, purchase or receive payments in currencies other than AED. A statement should use a consistent reporting currency and apply the business’s accounting treatment for foreign-currency transactions. Exchange-rate movements can affect the AED value recorded, even when the foreign-currency amount has not changed.
Practical controls include:
- Reconciling each business bank account to the accounting records.
- Recording petty-cash movements promptly.
- Separating transfers between the business’s own accounts from genuine income or expenditure.
- Checking whether foreign-currency balances have been translated consistently.
- Investigating unexplained differences between the statement and bank balances.
How operating, investing and financing cash flows work
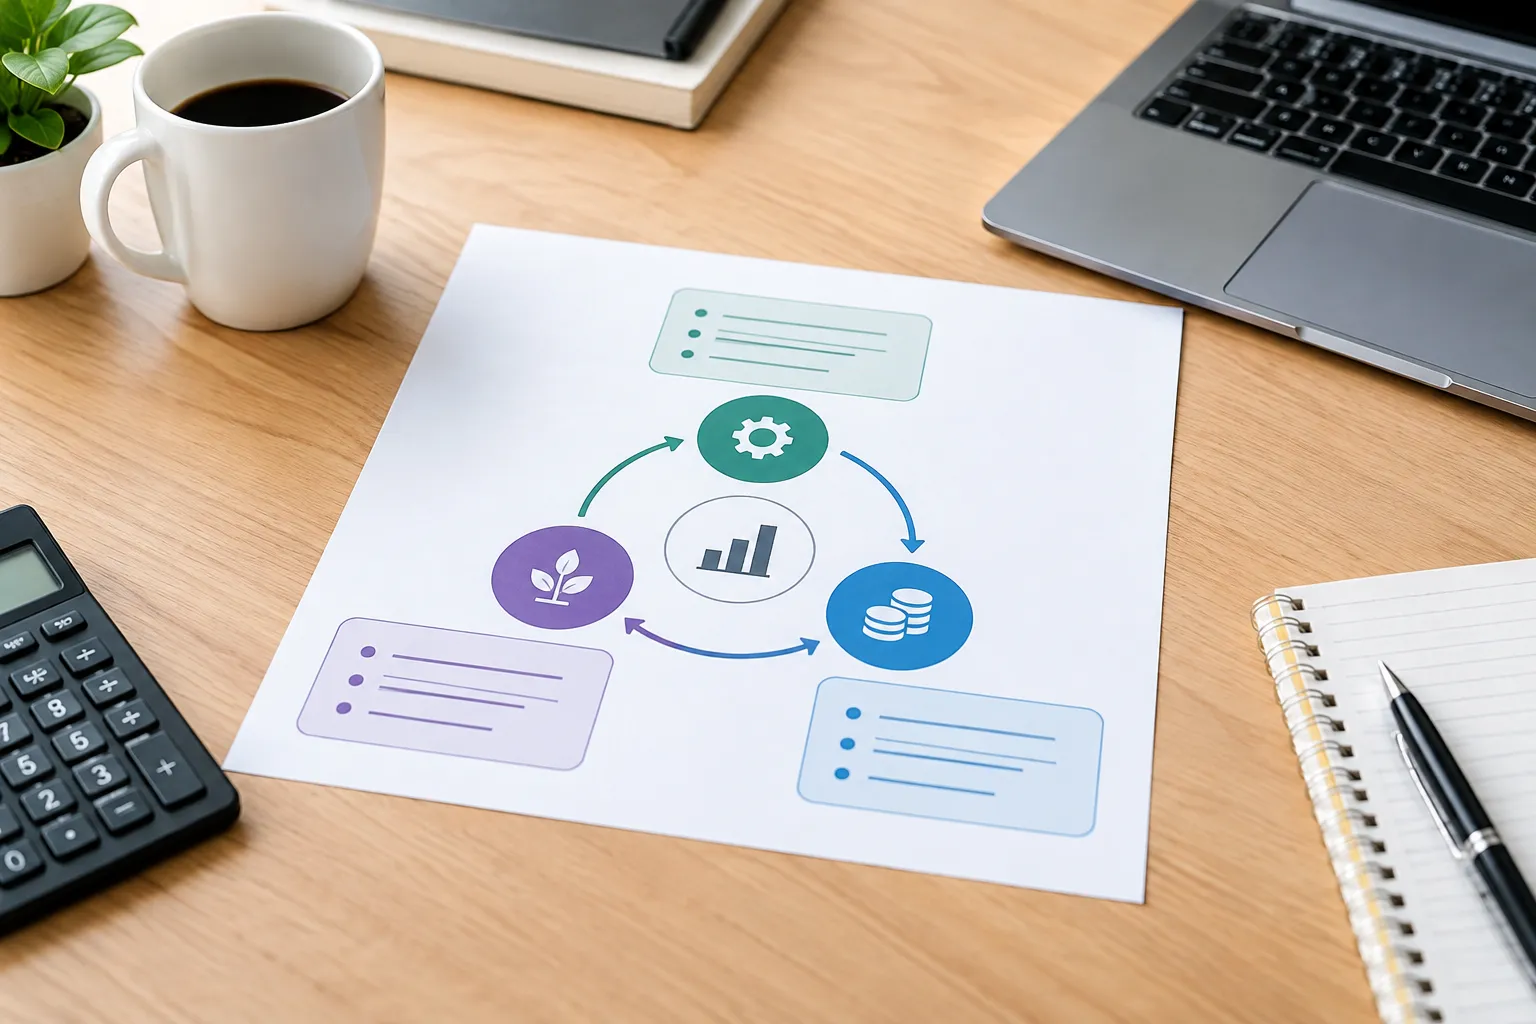
The three sections help an owner understand the reason behind a change in cash. A growing business may have positive operating cash flow but negative investing cash flow because it is purchasing equipment. Another business may show positive cash overall only because it has borrowed money.
Operating cash flow from day-to-day trading
Operating cash flow covers recurring business activity. Common examples include:
- Collections from customers.
- Payments to suppliers.
- Payroll and related employment costs.
- Rent, utilities and regular operating expenses.
- Tax payments where applicable.
- Receipts from providing services or selling products.
- Payments for routine professional, technology and administrative services.
Receivables and payment terms are particularly important. A business that sells on credit may record strong sales while waiting weeks or months for customers to pay. This creates a working-capital gap: the business must fund operations before receiving the cash generated by sales.
A useful question when considering working capital what is is: how much money is tied up in ordinary trading before it becomes available again? Receivables, inventory and supplier terms all influence the answer.
If unpaid invoices are creating a temporary gap, an owner may review whether invoice financing UAE is relevant. Suitability depends on the invoices, customers, documentation and the assessment of the finance provider; it is not a substitute for reviewing collection processes and customer credit terms.
Investing cash flow for assets and growth
Investing cash flow covers purchases and disposals of assets expected to support the business over more than one operating period. Examples may include:
- Buying machinery or other equipment.
- Purchasing delivery vehicles.
- Acquiring computers or significant business systems.
- Paying for property or substantial fit-out work.
- Proceeds from selling a long-term business asset.
Expansion can reduce cash even when it is commercially sensible. A trading business that buys vehicles for a new delivery route may have lower available cash immediately, with the expected benefit appearing later through additional sales or improved capacity.
The statement should therefore be read alongside the business plan and budget. A large investing outflow may be planned and affordable, or it may place too much pressure on short-term liquidity.
Financing cash flow from debt and equity
Financing cash flow records how the business obtains and returns capital. It may include:
- Loan or finance proceeds.
- Repayments of loan principal.
- Owner capital introduced into the business.
- Equity investment.
- Dividends or owner drawings, depending on the accounting presentation.
- Other qualifying financing movements.
Loan proceeds increase cash but are not sales. Loan principal repayments reduce cash but are not operating expenses in the same way as ordinary supplier costs. Interest may be presented according to the applicable accounting treatment and reporting policy.
This distinction matters when assessing repayment capacity. A business can have a positive closing balance after borrowing while still producing insufficient operating cash to support future repayments. Owners should consider both the amount borrowed and the recurring cash generated by trading.
How to prepare a cash flow statement step by step
A reliable statement depends on complete records and consistent classification. The process below is a practical monthly routine rather than a substitute for accounting advice or a formal reporting framework.
Choose the direct or indirect method
The direct method lists major cash receipts and payments, such as customer collections, supplier payments, payroll and rent. It gives a straightforward view of where operating cash came from and where it went.
The indirect method starts with accounting profit and adjusts it for non-cash items and changes in working capital. It may add back non-cash expenses and account for movements in receivables, inventory and payables.
The direct method can be intuitive for owners managing daily cash. The indirect method can be practical where the accounting records already produce an accrual-based profit figure and balance-sheet movements. The important requirement is that the final operating cash figure is supported by the underlying records.
Adjust for working capital movements
Working capital generally relates to short-term operating assets and liabilities. For many SMEs, the most important items are:
- Trade receivables: amounts customers owe.
- Inventory: stock purchased but not yet sold.
- Trade payables: amounts owed to suppliers.
- Other current assets and liabilities connected with operations.
Under the indirect method, an increase in receivables usually reduces operating cash because sales have been recognised but not collected. An increase in inventory can also reduce cash because money has been spent on stock. An increase in payables may temporarily increase operating cash because the business has received goods or services without paying yet.
For example, suppose a company’s receivables increase by AED 40,000 during a month while sales are recorded in full. That increase indicates that AED 40,000 of recognised revenue has not yet been collected, subject to the accounting records and other adjustments.
Working-capital movements should be interpreted over time. A one-month increase in receivables may reflect normal billing cycles, while a repeated increase may indicate slower collections or overly generous payment terms.
Reconcile opening and closing cash
The final statement should connect logically:
Opening cash balance
+ Net operating cash flow
+ Net investing cash flow
+ Net financing cash flow
= Closing cash balance
Compare the calculated closing balance with bank statements and verified petty-cash records. If the figures do not agree, check for:
- Missing bank accounts or transactions.
- Transfers recorded as income or expenses.
- Loan proceeds or repayments classified incorrectly.
- Unpresented payments or deposits.
- Foreign-currency conversion differences.
- Duplicate entries.
- Owner drawings or contributions omitted from the records.
A monthly reconciliation makes errors easier to identify than waiting until the end of the financial year. It also gives the owner a more current view of available cash.
When supplier payments are putting pressure on liquidity, the statement can help identify whether the issue is a short-term timing gap or part of a wider financial problem. For example, owners considering How can a UAE distributor pay should first understand upcoming obligations, receivables and the likely repayment effect of any funding.
Cash flow statement example for a UAE SME
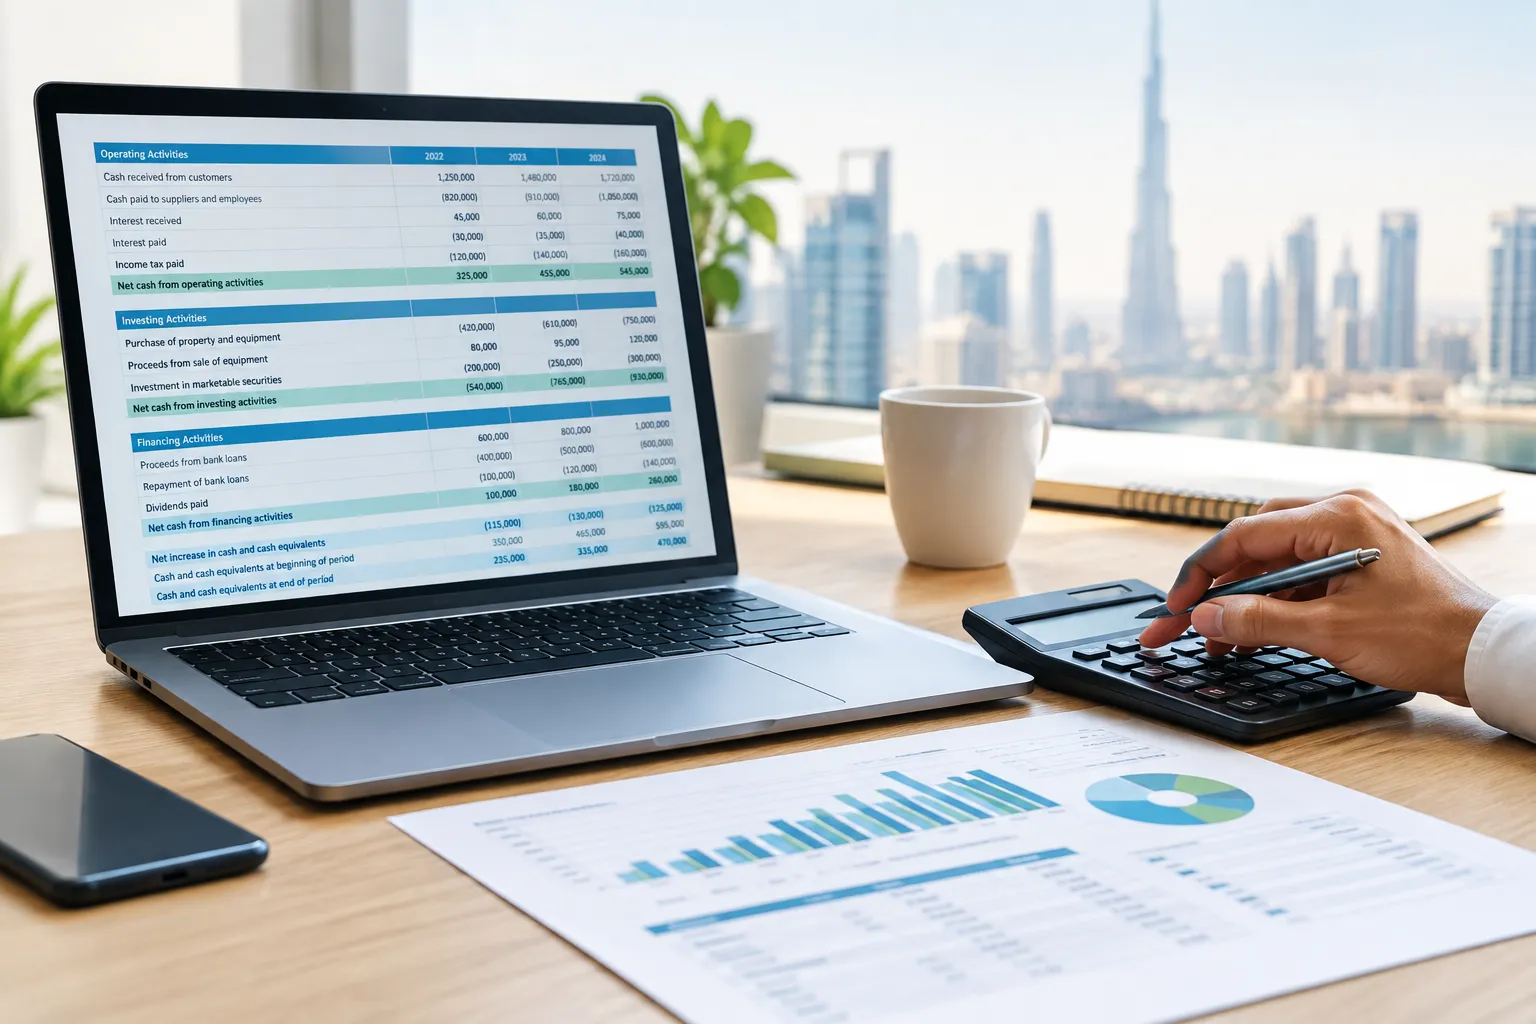
The following simplified cash flow statement examples use illustrative figures for explanation only. They do not represent a forecast, quotation or expected result for any business.
A simple monthly statement in AED
Assume a UAE trading business begins the month with AED 120,000 in cash.
| Section | Cash movement | AED |
|---|---|---|
| Operating activities | Customer collections | 280,000 |
| Operating activities | Supplier payments | (190,000) |
| Operating activities | Payroll, rent and other operating costs | (55,000) |
| Net operating cash flow | 35,000 | |
| Investing activities | Purchase of delivery equipment | (45,000) |
| Net investing cash flow | (45,000) | |
| Financing activities | New finance received | 60,000 |
| Financing activities | Principal repayment | (15,000) |
| Net financing cash flow | 45,000 | |
| Net increase in cash | 35,000 | |
| Opening cash | 120,000 | |
| Closing cash | 155,000 |
The business generated AED 35,000 from operating activities. It spent AED 45,000 on equipment and received a net AED 45,000 from financing. The closing balance increased by AED 35,000 to AED 155,000.
What the example reveals about cash health
The statement shows a positive operating cash flow, which is a useful sign that normal trading produced cash during the month. However, one month does not establish a trend. The owner should review several periods and compare actual collections with invoice due dates.
The equipment purchase reduced cash, but it may support capacity or revenue in future periods. The new finance increased cash, while the principal repayment created a continuing obligation. The business should assess whether future operating cash can cover scheduled repayments alongside payroll, suppliers and other commitments.
The closing balance also does not mean that all AED 155,000 is freely available. Some of it may be required for supplier payments, taxes, payroll, deposits or other near-term obligations.
Common classification and timing mistakes
Common errors include:
- Treating loan proceeds as sales revenue.
- Treating an unpaid invoice as a cash receipt.
- Omitting payments made from a secondary bank account.
- Recording a capital purchase as an ordinary recurring expense without considering the reporting treatment.
- Forgetting owner withdrawals or contributions.
- Treating transfers between the business’s own accounts as income.
- Ignoring credit-card settlements or payment-platform timing.
- Failing to reconcile foreign-currency balances.
- Recording supplier invoices but overlooking the eventual payment date.
These mistakes can make cash availability appear stronger or weaker than it really is. A consistent chart of accounts, timely bank reconciliation and clear separation between business and personal transactions reduce the risk.
Using cash flow to assess UAE SME funding needs
A cash flow statement does not decide whether a business should borrow or seek investment. It helps the owner describe the requirement more precisely and discuss it with a funding provider.
The key questions are:
- How much cash is needed?
- When is it needed?
- What creates the gap?
- How long will the gap last?
- What source of cash will repay the facility?
- What happens if collections are later than expected?
Separate a temporary gap from a structural shortfall
A temporary gap may occur when a business pays suppliers before collecting customer invoices, experiences seasonal demand or invests ahead of a confirmed opportunity. The underlying business may be sound, but timing creates pressure.
A structural shortfall is more persistent. It may result from weak margins, consistently slow collections, excessive stock, high fixed costs or operating cash flow that remains negative. Borrowing may delay the problem rather than resolve it.
Rapid growth can create either situation. More sales may increase receivables and inventory requirements before cash is collected. Compare sales growth with operating cash flow, debtor days, supplier terms and available liquidity.
A simple forecast can extend the cash flow statement into the future. List expected customer receipts and payments by week or month, then test a slower-collection scenario. This can reveal a funding requirement before it becomes an urgent supplier or payroll issue.
Match funding to the cash requirement
The appropriate finance type depends on the purpose, timing, business profile and assessment by the provider. In broad terms:
- Invoice financing may be relevant where eligible unpaid customer invoices create a short-term working-capital gap.
- Trade finance may help address particular import, export or supplier-payment requirements, subject to the transaction and provider criteria.
- Asset finance may align a long-term equipment or vehicle purchase with the asset’s intended business use.
- A term loan may be considered for a defined business requirement where scheduled repayments fit projected cash flow.
- Equity can provide capital without the same repayment structure as debt, but it involves ownership and investment considerations.
The facility should match the cash requirement rather than simply the maximum amount available. Funding does not correct poor collection practices, unprofitable sales or an unsustainable cost base. Owners should test repayments against conservative cash-flow assumptions.
Prepare cash flow information for funders
A clear funding discussion may be easier when the business can provide organised information such as:
- Recent cash flow statements.
- Profit and loss accounts and balance sheets.
- Current and projected bank statements or transaction records.
- A list of outstanding customer invoices.
- Supplier balances and payment terms.
- Details of existing borrowing and repayment schedules.
- A short explanation of the funding purpose.
- A cash-flow forecast showing the expected use and repayment source.
- Corporate, ownership and identification documents where requested.
Requirements vary between banks, fintechs and other finance providers. The business should answer questions accurately and explain unusual movements, delayed payments, major contracts or large one-off expenses.
FAQ about cash flow statements
What is on a cash flow statement?
A cash flow statement shows opening cash, cash movements from operating, investing and financing activities, and the resulting closing cash balance for a defined period.
What are the three types of cash flow statements?
The three sections are operating cash flow, investing cash flow and financing cash flow. They describe cash from trading, long-term assets, and capital or borrowing movements.
How to prepare a cash flow statement?
Gather bank and accounting records, classify cash movements, adjust for working-capital changes where required, and reconcile the calculated closing cash with verified balances.
What is the best definition of cash flow?
Cash flow is the movement of money into and out of a business during a period. It measures liquidity movement, not simply sales or accounting profit.
What is the cash flow formula?
The basic formula is opening cash plus operating cash flow, investing cash flow and financing cash flow, which equals the closing cash balance.
What is another name for cash flow?
Cash flow is sometimes described as the movement or generation of cash. It should not be confused with profit, revenue or the cash balance at one particular date.
How can a cash flow statement help an SME secure business finance?
It shows funders how the business generates and uses cash, highlights the purpose of the requirement, and helps explain whether projected cash may support repayments.
How can seasonal UAE businesses manage cash flow more effectively?
Seasonal businesses can map receipts and payments by month, build a forecast for quieter periods, monitor inventory and negotiate payment timing where appropriate.
Make the cash flow statement part of your monthly routine
A cash flow statement is most useful when it is updated regularly rather than prepared only when a funding application is due. Set a recurring monthly process to reconcile bank balances, review customer collections, update supplier obligations and compare actual results with the forecast.
Investigate material variances. If collections are below plan, identify the affected invoices and expected payment dates. If inventory spending is higher than expected, review purchasing and sales assumptions. If operating cash flow is repeatedly negative, examine pricing, margins, payment terms and fixed costs before relying on additional borrowing.
For a growing UAE SME, the statement also creates a clearer basis for discussing funding. It can help distinguish a short-term working-capital requirement from a longer-term investment need, explain the effect of delayed payments and show how a proposed facility would fit into the business’s cash cycle.
SYG International arranges SME funding solutions across the UAE, including debt and equity options through banks and fintechs. The first practical step is often not choosing a facility, but understanding the cash position, the timing of the gap and the finance requirement that follows from it.
SYG International advises on, structures and arranges debt and equity funding for SMEs and mid-market companies across the UAE, working through banks, fintechs, private lenders and investors. SYG does not lend.
Want to know which funding option fits your business? Talk to SYG International.
Discuss your fundingSYG International advises on, structures and arranges funding. We do not lend. Final decisions, pricing and terms rest with each funding institution. This article is general information, not financial advice.